State Adjusting Services

Fire and smoke damage insurance claims in Illinois

One fire, four claims: the building, the smoke, your belongings, and where you live or work meanwhile. We document all four.

  • $0 upfront
  • Fee from the recovery only
  • Homes and commercial buildings
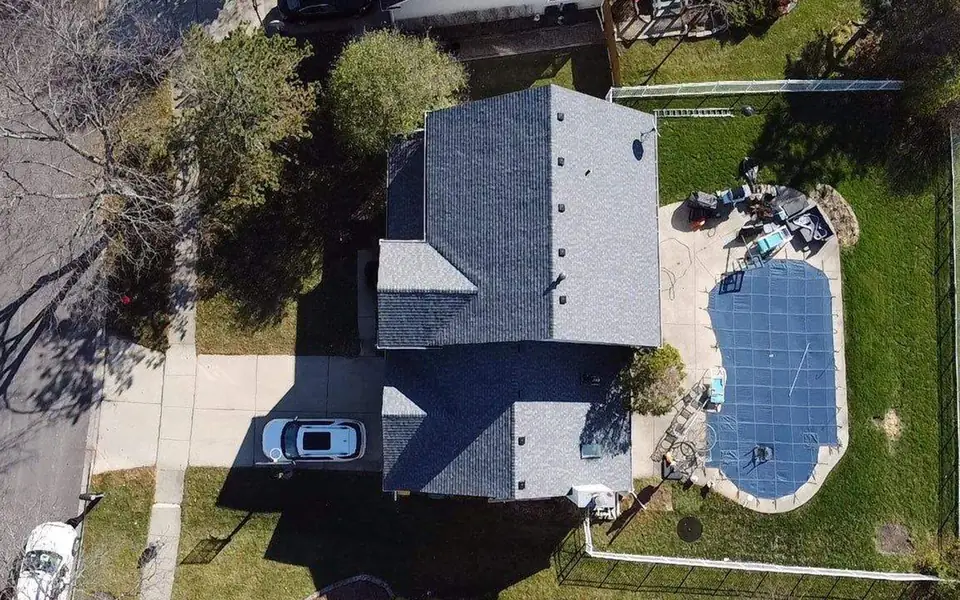
Aerial view of a two-storey house with a dark grey shingle roof, a white SUV in the driveway and a pool under a blue cover in the fenced backyard
Fire & smoke claim · approvedSiding melted by a grill, replaced across the whole wall.

What one fire damages, and what first estimates leave out

Gold: what we most often add to the carrier’s estimate.

Framing and roof

Charred joists and decking, heat-warped windows.

Water from the hoses

Soaked drywall and floors in rooms the flames never reached.

Belongings

Furniture, clothing, electronics, valued item by item.

Smoke in ducts

Soot rides the HVAC system into cabinets and wall cavities.

Often missed
Code upgrades

Wiring and smoke alarms rebuilt to today’s code, if the policy has ordinance or law cover.

Often missed
Months away from home

Rent, extra food and mileage for the real rebuild time.

Often missed

A small fire loss, paid as a full wall instead of a patch

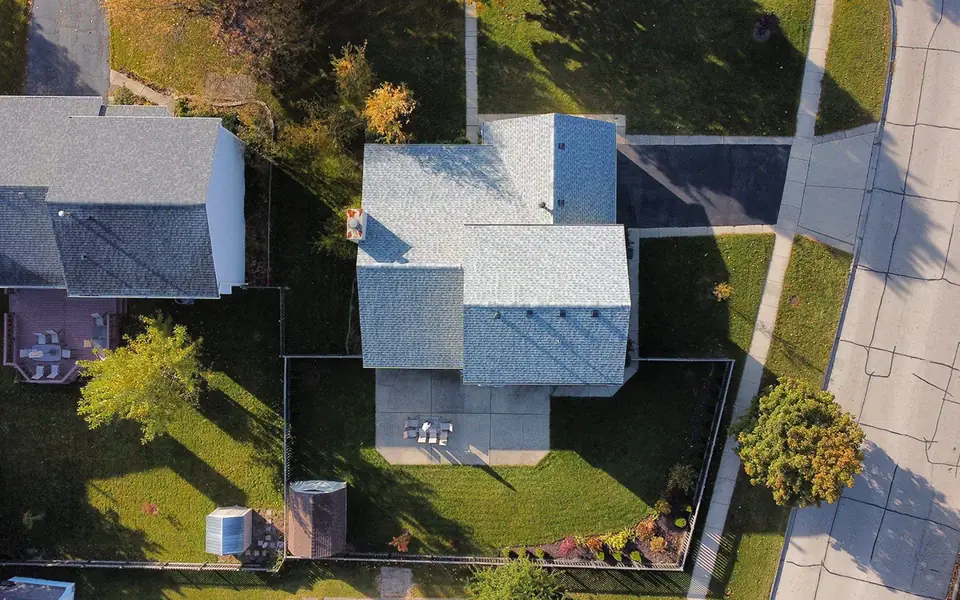
Aerial view of a house with a pale grey shingle roof, a concrete patio with a table and chairs, and two garden sheds in the fenced yard
Fire & smoke damage · approved

Grill heat melted the siding; the whole elevation was replaced

New panels would not match the old ones, so we claimed the entire side of the house instead of a few panels. Approved and built.

  • Whole elevation replaced
  • Color match won
  • Building inspection passed

“…taking over the whole claim process from the beginning till the end.” Aleksey Babin

All results
Commercial fire and smoke claims: what a business policy adds

Shops, offices, warehouses. Your declarations page shows which of these you bought.

Building

Structure, fixtures and the systems smoke moves through.

Bring: floor plans

Stock and equipment

Inventory and machinery hurt by heat, soot or water.

Bring: inventory records

Business income

Net income lost while you cannot operate.

Bring: profit and loss statements

Extra expense

A temporary site, rented equipment, overtime.

Bring: invoices paid since the fire

Closed for weeks? See business interruption claims.

Three ways a fire claim loses money

  1. Smoke written off as cleanableWe record residue in ducts and porous materials and price what cleaning cannot fix.
  2. Contents at a used-goods priceWhere the policy pays replacement cost, we claim the withheld part once items are replaced.
  3. Living expenses cut shortWe tie payments to the actual construction schedule.
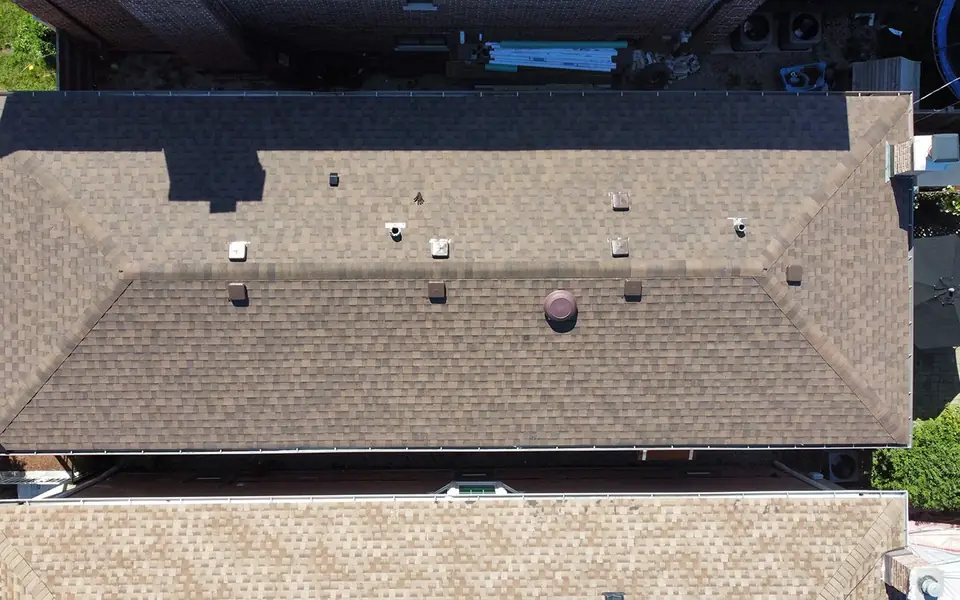
Overhead view of a long brown shingle roof with box vents and one round turbine vent, with a second roof below it

What Illinois law forbids a public adjuster at a fire

Rules from 215 ILCS 5/1590 that bind us and anyone who knocks on your door.

Not at the scene

No one may offer to represent you while the fire department is still at the property.

215 ILCS 5/1590(b)
No salvage deals

No share in your property’s salvage without your written permission after settlement.

215 ILCS 5/1590(e)
Not a fire official

No posing as the fire department or a fire investigator.

215 ILCS 5/1590(m)
No cash advances

No money advanced during the claim, except emergency services.

215 ILCS 5/1590(j)(7)

Your receipts burned. The proof of what you owned did not

We build the room-by-room inventory with you from these sources.

  • Card and bank statementsEach purchase is a dated line.
  • Online order historyWhat you bought, when, for how much.
  • Phone photo backupsRoom photos show items in the background.
  • Product registrationsModel and serial numbers on file.
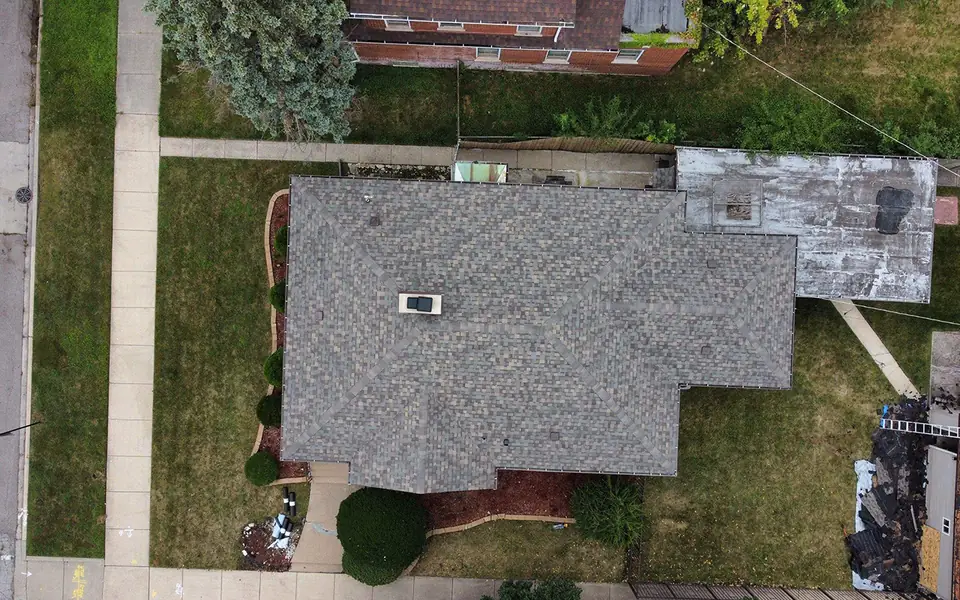
  • Aerial view of a house with a grey shingle roof, a flat roof section at the back, and a ladder and pile of roofing debris at the side
“You helped me a lot. Thank you!! And thanks for consulting my brother — you resolved all problems with his insurance company!!!”
Madison Vrieling · Google review · August 2023
4.934 Google reviewsRead them

Start a free review of your fire claim

  1. Tell us what burnedHome or business, and what the carrier has said so far.
  2. We read the policyIncluding the living-expense and business income limits.
  3. We document, price and negotiatePaid as a share of the recovery, never upfront.

Start with four fields

Rather send photos and a longer note? Open the full form. Only the adjuster on your claim sees what you send.

Fire and smoke claim questions

Call Monday through Friday, 7 AM to 7 PM, and Saturday and Sunday, 9 AM to 5 PM.

(630) 297-8136
The insurer offered to settle a few weeks after the fire. Should I accept?

Check what it leaves out first. Contents, code upgrades and living expenses are often still open that early.

Our business is closed after a smoke loss. What can the policy pay besides the building?

If you bought business income and extra expense cover: lost net income and the added cost of operating elsewhere.

Can a public adjuster sign me up while firefighters are still at the house?

No. Illinois law bars that while the fire department is engaged at the premises. You can report it to the Illinois Department of Insurance.