
Called wear and tear
The carrier says the shingles were old, not storm-hit. We document the storm date and the damage slope by slope.

Wind, hail and falling branches damage more than the roof. We document the whole loss and negotiate it as one claim.
The carrier says the shingles were old, not storm-hit. We document the storm date and the damage slope by slope.
A few shingles priced, the siding and gutters left out. We write the whole scope at replacement cost.
Calls go unanswered and inspections move. We handle every contact with the carrier for you.
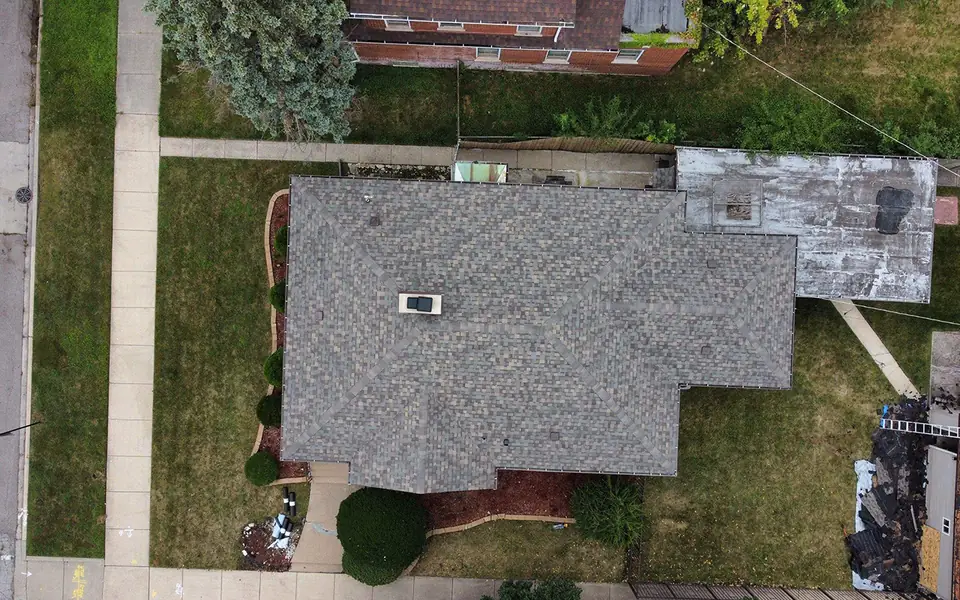
Every elevation documented, estimate built at real replacement cost. The settlement covered the work.
“When they said they will do it all through my insurance — it was true!” Valentina Babin
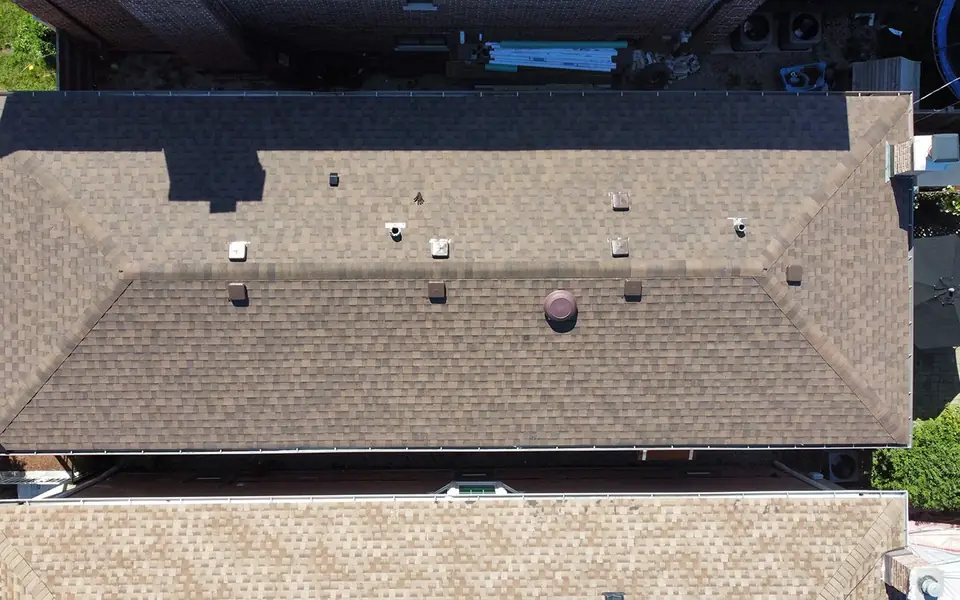
Every affected system was valued as one loss, not only the most visible part.
“Helped me to get money from insurance for all the damages I had after a storm.” Marta Babiy
Gold tiles: what we most often find missing from a first estimate.
Lifted, creased or missing shingles after wind; bruised shingles after hail.
Dents on the same elevations as the roof belong in the same claim.
Broken glass, torn screens, dented door panels.
Ceiling stains and wet insulation traced back to an opening the storm created.
Often missedCovered under the “other structures” part of most homeowners policies.
Often missedTarping, board-up, debris removal, and living expenses if part of the home was unusable.
Often missedEvery public adjuster in Illinois works under the same rules. Check them before you sign with anyone.
The most a public adjuster may charge on a home claim, as a share of what the insurer pays.
215 ILCS 5/1570The contract has to state the full fee and that cap.
215 ILCS 5/1575You may cancel the contract within 5 business days after your insurer receives it.
215 ILCS 5/1575Only a licensed public adjuster may negotiate your claim. Ask for the licence and verify it.
Illinois Department of InsuranceThank you for great service! Claim approved for full roof replacement, siding and gutters as well!
Cannot thank you guys enough for claiming my insurance and helping me fix my roof for free! The service was very efficient and clear. Highly recommended!
Great customer service. I was uninformed on this kind of work but this business helped me step by step with fixing my problem.
Two claims can mean two deductibles. If one storm caused the loss, it is one occurrence, and we document the weather event and damage chain so it is paid as one loss.
It is a triage visit. Our storm inspection covers the roof, every elevation, interior water and detached structures, and typically takes hours.
Not necessarily. Underpaid and denied claims can be re-opened with new documentation. Send us the carrier’s estimate and we will tell you what is missing from it.