

Property insurance claims we handle in Illinois
Twenty kinds of home and business loss, from a hailstorm to a denied claim. We represent the policyholder, never the insurance company.
- $0 upfront
- Fee from the recovery only
- Licensed in Illinois
- Homes & businesses
Find your claim by what happened
Weather and the roof
- Hail DamageBruised shingles, dented metal
- Storm DamageRoof, siding and interior from one event
- Wind DamageLifted, creased or missing shingles
- Tornado DamageRacked framing, roof uplift
- Ice & Snow DamageIce dams and snow load
- Roof CollapseHow your policy defines collapse
- Lightning DamageThe strike, the wiring, the electronics
- Power Surge DamageWho pays depends on where the current came from
- Commercial Hail DamageFlat roofs and rooftop units
- Hail Damage in Geneva, ILCity permit items and Historic District review
Water inside the building
Fire, smoke and blast
Crime, business and denials
- Vandalism & TheftBreak-ins and damage at home
- Commercial Theft & BurglaryStock settled on inventory records
- Business InterruptionLost income while you are closed
- Rental Property ClaimsThe building and the lost rent
- Denied ClaimsThe letter checked against the policy
- Underpaid ClaimsMissing line items and held-back depreciation
Different claims, the same clients’ verdict
Thank you so much, you guys are AWESOME. They helped me to get a new siding for my house absolutely free. My insurance paid for it. Thanks again guys, especially Anjelica. You are the best!!!
Very effective representing us. Results couldn’t be better.
Highly recommended. State Adjusting Services did an amazing job with my claim. Thank you.
Home policy or business policy: which part pays
Homeowners policy
Each part has its own limit.
- Dwelling
- The house itself: roof, siding, attached garage.
- Other structures
- Fences, sheds and a detached garage.
- Personal property
- Furniture, clothing, electronics.
- Loss of use
- Extra living costs while the home cannot be lived in.
- Endorsements
- Added cover such as water backup, up to its own limit.
Commercial property policy
Parts a home policy never had, if you bought them.
- Building
- The structure, or a tenant’s improvements.
- Business property
- Stock, equipment and furniture.
- Business income
- Lost profit and ongoing costs while you are shut. Details.
- Extra expense
- What it costs to keep operating somewhere else.
- Crime cover
- Money and employee theft, often a separate policy. See commercial theft.
Two approved claims, two different causes
All results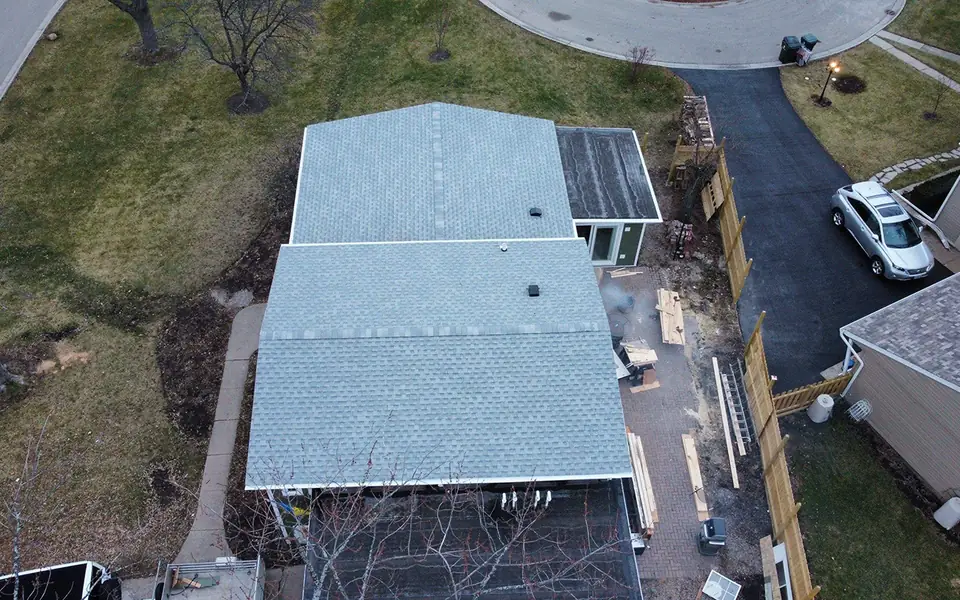
Roof, siding and gutters in one hail claim
Siding and gutter dents on the same sides as the roof damage went into the same claim. The full scope was approved.
- Roof system
- Siding
- Gutters & downspouts
“Claim approved for full roof replacement, siding and gutters as well!” Oleg Babin
Siding melted by a grill: the whole elevation replaced
New panels could not match the old ones, so we argued for replacing that whole side. Approved, and it passed the building inspection.
- Full siding replacement
- Matching argued
- Inspection passed
What Illinois requires of every public adjuster
They apply to every claim type above. Ask any adjuster how they meet them.
Minimum bond or letter of credit an adjuster must keep, to pay people harmed by errors or fraud.
215 ILCS 5/1560Claim money held for you goes into a non-interest-bearing escrow or trust account.
215 ILCS 5/1580The adjuster records every payment received in connection with your loss, from any source.
215 ILCS 5/1585Those records are kept at least 7 years after your claim ends, open to the Director of Insurance.
215 ILCS 5/1585My damage fits two of these pages. Which one is mine?
Either one. Wind that opens a roof and lets rain in causes two kinds of damage from one event. We review it as one claim.
Do you take business properties as well as homes?
Yes. We handle residential and commercial claims, including stock, equipment and lost income when the policy carries that coverage.
What does the review cost if I do not hire you?
Nothing. The review is free. If we take the claim, our fee comes only from the recovery.