
Public adjuster questions, answered for Illinois policyholders
What we do on a claim, what it costs, and which Illinois rules to check before you sign.
- $0 upfront
- Fee from the recovery
- Lincolnshire, IL · since 2019
Three adjusters can look at your claim. Only one is hired by you.
Two claims that started with a question
All results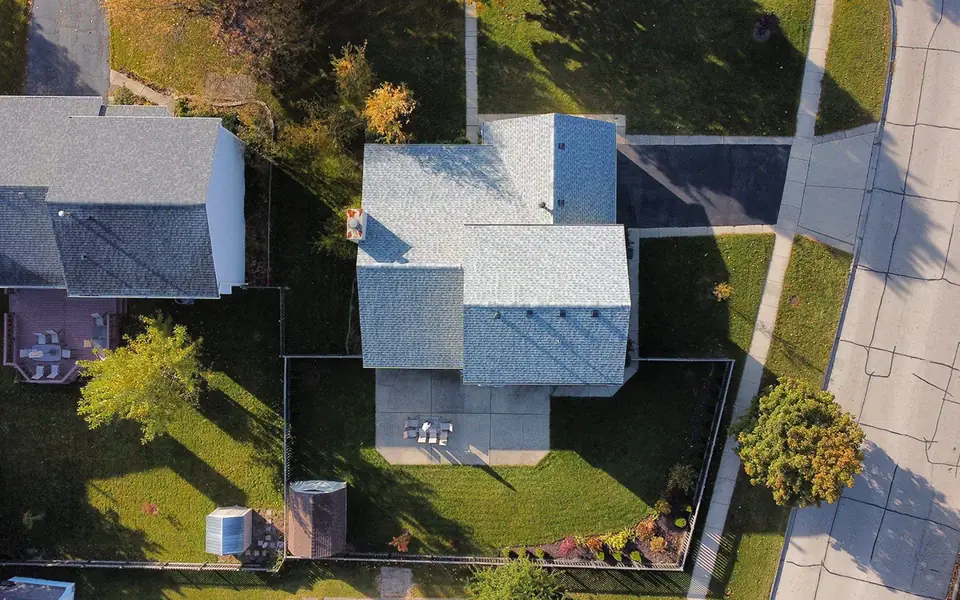
Siding melted by a grill: the whole elevation replaced
Asked: is a small loss worth a claim? New siding can’t be blended into old, so we argued for the whole wall.
- Full siding replacement
- Inspection passed
“Guys got me approved for the full siding replacement on the house.” Aleksey Babin
A flooded basement the owners thought was excluded
Asked: is basement water ever covered? We traced the cause and matched it to the policy wording.
- Cause established
- Coverage identified
“They helped us work around insurance with our flooded basement.” Yaryna Dovhan
Have these open when you call us
- Declarations pageYour limits and deductible.
- Claim numberIf you already reported the loss.
- Every insurer letterEstimates, requests, a denial.
- Photos and videoTaken before cleanup.
- ReceiptsTarps, board-up, a hotel stay.
- The date of the lossAs close as you know it.
Missing half of this list? Call anyway. The first review is free.
Three Illinois rules worth checking before you hire anyone
Article XLV of the Illinois Insurance Code.
- Your own property claims onlyFirst-party claims under policies insuring your real or personal property.215 ILCS 5/1510
- Licensed people onlyNo unlicensed employee may do licensed work.215 ILCS 5/1590(c)
- Contractor ties disclosedAny pay from a construction or board-up firm on your loss is disclosed to you.215 ILCS 5/1590(g)
“I had a very positive experience working with this public adjuster company. From the very beginning, the team demonstrated a high level of professionalism, attention to detail, and a genuine commitment to helping their clients. I highly recommend this company to anyone looking for a reliable and experienced professional who truly works in their client’s best interest.”
Your question, answered for your own policy
- Send four fieldsName, phone and email. Office hours: Mon–Fri 7–7, Sat–Sun 9–5.
- We read the policy and lettersAnd say if you need us.
- You decideThe fee is in the contract, paid from the recovery.
Questions Illinois policyholders ask us first
Do I have to hire a public adjuster to file a claim?
No. You can deal with your insurer yourself, and Illinois bars a public adjuster from telling you otherwise (215 ILCS 5/1590(m)).
How do you get paid?
A share of what the insurer pays, set in the written contract. Nothing upfront. On a home claim Illinois caps it at 10% (215 ILCS 5/1570).
Can I cancel after I sign?
Yes, within 5 business days after your insurer receives the contract (215 ILCS 5/1575).
What claims do you handle?
Property claims under your own policy, home or commercial: hail, wind, water, fire, theft and more. We do not handle injury claims.
My claim was denied or underpaid. Is it too late?
Often not. Send the denial letter or estimate with your policy, and we will say if re-opening it is worth it.
What is your link to State Restoration Services?
Our construction partner, a roofing and exterior contractor. Using it is optional; Illinois requires such ties to be disclosed.