
Church insurance claims in Illinois
When hail, fire or water reaches a sanctuary, the claim has to price a steeple, windows and an organ that no price book lists, and keep the congregation's week going. We are licensed Illinois public adjusters, and we prepare and present that claim for the church.
One week in a church building after a fire, and the line of the policy each loss points to
- Sun
Worship moves to a rented school gym, with chairs and sound hired in
Extra expense
- Mon
The office is smoke-damaged: computers, files and records of members
Business personal property, records extension
- Tue
The food pantry loses its freezers, shelving and stock
Business personal property
- Wed
The weekday preschool the church runs stays closed, and tuition stops
Business income
- Thu
Choir rehearsal stops: water reached the organ chamber
Building, if the organ is permanently installed
- Fri
The fellowship hall's walls, floor and kitchen are torn out
Building, plus code work under ordinance or law
- Sat
Groups that rent the hall are turned away, and the rent stops
Business income, rental value
Each line pays only if your declarations list it, and only up to its limit. We read the policy first and tell you which of these your church carries.
Two lanes of money, and the church fire that lost the second one
Most church policies pay in two steps. The first check is the actual cash value: the cost to repair less depreciation. The rest of the replacement cost waits until the work is done. In March 2026 the Seventh Circuit, the federal appeals court that covers Illinois, showed what happens when the work never starts.
What happened in Crothersville
The fire damaged the sanctuary, offices, classrooms and baptismal area. The carrier's letters asked for repairs and receipts within 180 days. For two years the church disputed the estimates and no rebuilding began. It sued in June 2020 and lost, and on appeal the court would not hear its argument that the price dispute excused the delay, because it was raised too late. Reported by Claims Journal.
A second church, and a 180-day line
After Hurricane Michael in Florida, the same carrier paid St. Michael's Anglican Catholic Church nearly $100,000 at actual cash value, then argued it owed nothing more because the church never formally chose actual cash value. That policy also let the church claim replacement cost later only if it gave notice within 180 days of the loss. The case is set out by Merlin Law Group.
What the board can put in writing in the first weeks
- Ask the carrier to pay the actual cash value now and the replacement cost when the work is done.
- Tell the carrier, inside any notice period the policy sets, that the church intends to claim replacement cost.
- Record in the minutes the policy's repair condition and its time limits, and who is watching them.
- Start the work nobody disputes while the disputed part is argued, and keep every invoice.
The held-back part is the depreciation, explained step by step in our guide to recoverable depreciation. Questions about suing belong with the church's attorney. We are public adjusters, and our work is the claim itself.
Who speaks for the church on the claim
A shop owner signs everything alone. A congregation decides by committee, and the carrier needs to know who it is talking to. Sorting this out in the first week saves months of letters.
| Who | Their part in the claim | What to check |
|---|---|---|
| The named insured | The party on the declarations page. Checks are written to that name. | In some denominations a diocese, conference or synod is named, not the local church. |
| Board, trustees, vestry or council | Votes to report the loss, approves emergency work and any contract with an adjuster or contractor. | Put each vote in the minutes, so members can see who decided what. |
| One authorized officer | Signs the sworn proof of loss and answers the carrier's letters. | The sworn form has its own rules, covered in our sworn proof of loss guide. |
| Treasurer or bookkeeper | Holds the records the income lines need: rent from groups, preschool tuition, emergency invoices. | Pull 12 months of income before the loss, so there is a baseline. |
| Building and grounds lead | Knows the roof's repair history, the boiler, the keys and who has been in the building. | Photos from before the loss, even old ones from events, help show what was there. |
| Mortgage lender | Often printed on the building check with the church. | How that check gets released is in our page on the mortgage company on the insurance check. |
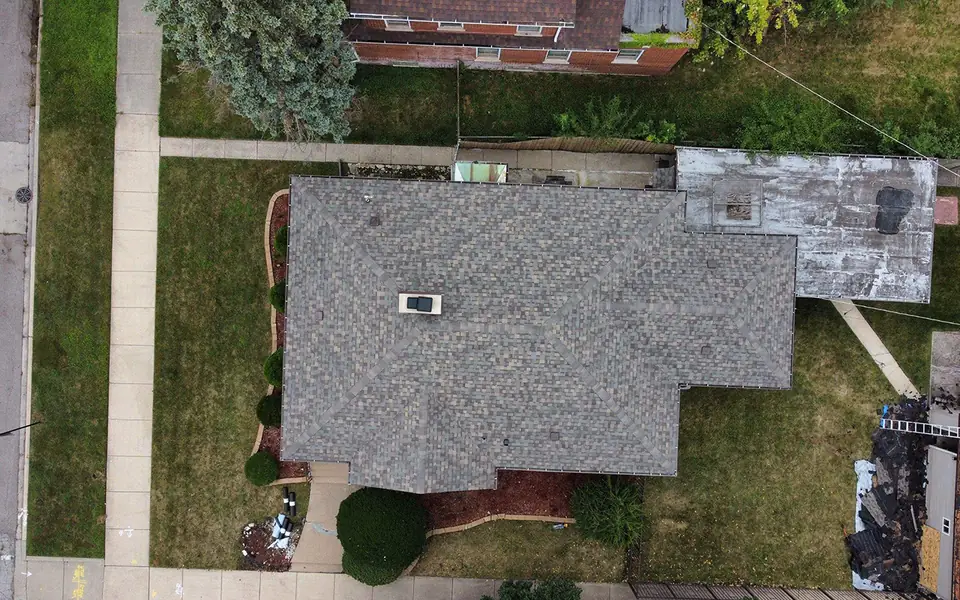
What we inspect on a church after a storm or fire
Church buildings are often three or four buildings joined over a century: a sanctuary, a parish hall, a school wing and a newer entrance. Each has its own roof and its own age, so each gets its own scope.
- Steep slate or shingle roofs over the nave, and the flat roofs and rooftop units over the additions
- The steeple, louvers, crosses and copper flashing, seen from a lift
- Every stained glass panel and its frame, inside and out
- Smoke residue in the organ chamber, the ductwork and carved woodwork
- Code work an older building needs once it is repaired, such as wiring, exits and accessibility
Flat roofs and rooftop equipment are covered in detail on our commercial hail damage page. When repairs trigger current codes, our guide to ordinance or law coverage shows which line pays. A church with a school or rental tenants also meets the coinsurance clause explained on our commercial property claims page.
Ask for a review of your church's claim
We read the policy and the carrier's letters free, and tell the board plainly where the claim stands. Our office is in Lincolnshire, open seven days a week, and we are rated 4.9 from 33 Google reviews, all on our reviews page.
- The date of the loss and the address of each building
- The policy with its declarations page
- The carrier's estimate and letters, if any have come
- Any appraisal of the windows, organ or bells
What the State tells a board to check before it signs
The Illinois Department of Insurance requires a public adjuster to hold its license and use a written contract approved by the Director. You can confirm a license at (866) 445-5364, and you can cancel by certified mail within 5 business days of signing.
What pastors and church boards ask us
- Do you handle church insurance claims in Illinois?
- Yes. We represent owners of commercial buildings across Illinois, and a congregation's sanctuary, hall and school buildings are among them, on storm, fire, water and other property losses.
- Is a pipe organ covered as part of the church building?
- Often, when it is permanently installed, because commercial building wording includes permanently installed equipment. The standard form does not define that phrase, so check whether your policy schedules the organ, and have a builder's valuation ready.
- Will the insurer pay replacement cost if we have not started repairs?
- Many church policies pay replacement cost only for repairs made as soon as reasonably possible, and pay actual cash value until then. In March 2026 the federal appeals court for Illinois ruled for the carrier where a church never began its repairs.
- Does the policy pay to rent another place for services?
- Only if it includes extra expense coverage, which pays the reasonable added cost of carrying on while the building is restored, such as renting a hall. Your declarations page shows whether it is there.
- What does a church claim cost the congregation?
- Nothing at the start. We take an agreed share of the insurance money paid on this claim, written into a contract your board approves. If the carrier pays nothing, the church owes us nothing.