
Underpaid insurance claims in Illinois
The check will not pay for the repair. We compare the carrier’s estimate with the damage and supplement what it left out.
- $0 upfront
- Fee from the recovery only
- Licensed Illinois public adjusters
Two claims where the scope grew past the first estimate
All results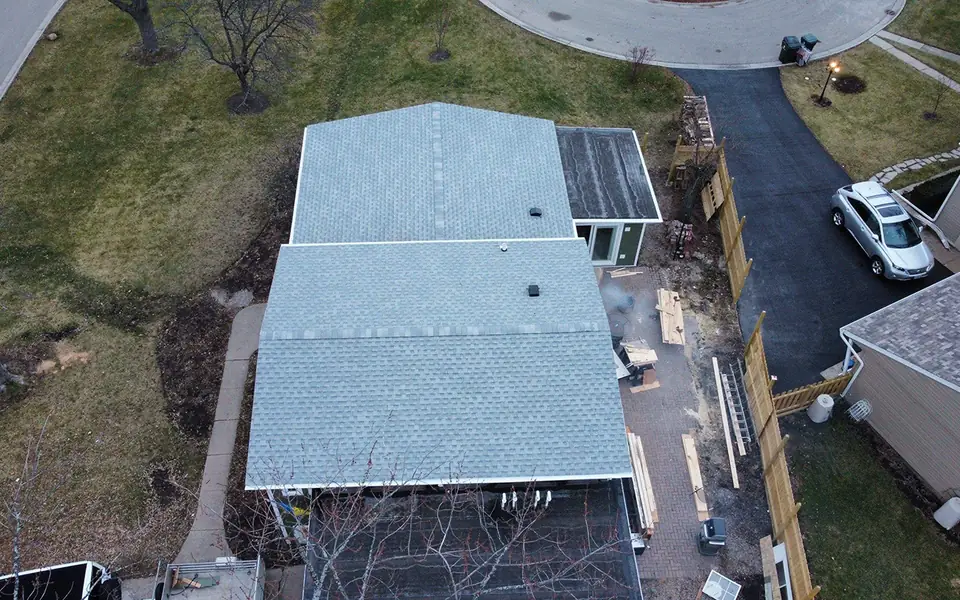
Roof, then siding and gutters on the same elevations
We documented the dented siding and gutters into the roof claim. All three were approved.
- Roof system
- Siding
- Gutters & downspouts
“Claim approved for full roof replacement, siding and gutters as well!” Oleg Babin
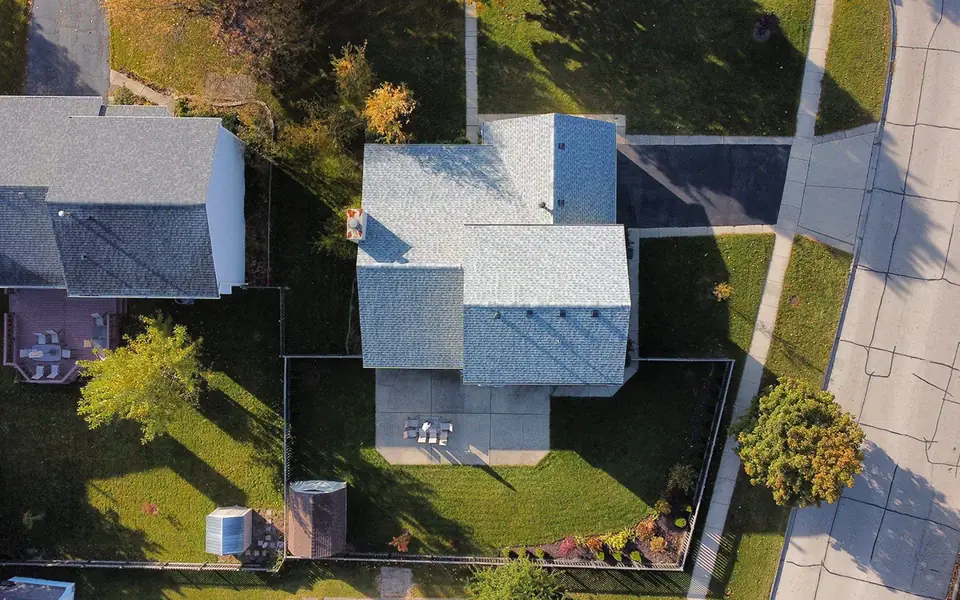
A few panels priced, a full elevation paid
New siding shows against old, so we claimed the whole affected wall, not a patch.
- Matching argued
- Full elevation
- Inspection passed
“Guys got me approved for the full siding replacement on the house.” Aleksey Babin
Three ways a covered claim ends up paid short
- The scope is too smallOne slope priced, not the roof; the stain, not the wet insulation behind it. We write every affected item.
- Depreciation is guessedAge and condition assumed, not measured. We request the worksheets and check each deduction.
- Prices no contractor will matchUnit costs below local trade rates. We price the repair at current cost.
Where the rest of your settlement is sitting
On a replacement cost policy, the first check is usually only part of the money.
A low replacement cost makes every number built on it low. That is where a supplement starts.
Most policies release it once the work is invoiced. See recoverable depreciation.
Once per occurrence. Two deductibles for one storm is worth questioning.
Some policies pay ACV only; see ACV vs replacement cost.
What Illinois requires when a property claim is paid on an estimate
50 Ill. Adm. Code 919.80. We are public adjusters, not attorneys.
A partial loss settled on the insurer’s estimate: you may request a copy of it.
919.80(d)(7)(C)A higher written estimate from you must get a prompt written answer naming a contractor, or a promise to pay reasonable costs above theirs.
919.80(d)(7)(C)On an ACV settlement, you may request the depreciation worksheets: age, condition, expected life.
919.80(d)(8)(A)Unresolved 75 days after reporting, or 25 after proof of loss: a written explanation is due.
919.80(d)(7)(B)“Throughout the adjustment process, they kept me updated every step of the way. But most importantly, the results they delivered were outstanding.”
Line items a supplement most often adds back
| Item | How it shows up in the carrier estimate | What the supplement documents |
|---|---|---|
| Matching | One slope or wall in material that no longer matches | Why a uniform result needs the full roof or elevation (matching in Illinois) |
| Code upgrades | Left out without checking the endorsement | What the building department requires, under ordinance or law coverage |
| Tear-out | The visible finish only | Drywall, insulation and trim removed to reach the damage |
| Hidden damage | Found after work starts | Photos of the open wall or roof deck, sent before it is closed |
How we review an underpaid claim
- Send the estimate and the policyFree review, no obligation.
- Re-inspect the propertyEvery elevation, interior and outbuilding, photographed.
- Write our own line-item estimateThen a written supplement for each missing or short item.
- Negotiate, then appraisal if neededWhen only the amount is disputed, the appraisal clause may apply.
Underpaid claim questions
I already deposited the insurance check. Can I still dispute the amount?
Usually, yes. Depositing a payment does not by itself close the claim. What matters is whether you signed a release, so read anything you are asked to sign and send it to us first.
What is a supplement?
A written request to add or reprice items on an open claim, backed by photos and a line-item estimate. See insurance claim supplements.
The claim was closed months ago. Can it be reopened?
Often, if the damage still exists and the policy’s time limits have not run out. See reopening a settled claim.